
Biweekly vs monthly payment calculator
Biweekly payments, and the free way to get the same result. Half a payment every fortnight is 26 half-payments a year, which is thirteen monthly payments instead of twelve. That thirteenth payment is where essentially all of the saving comes from.
Biweekly payment calculator
Biweekly schedule
Periods are fortnights, so 26 rows make up a year.
What is actually happening
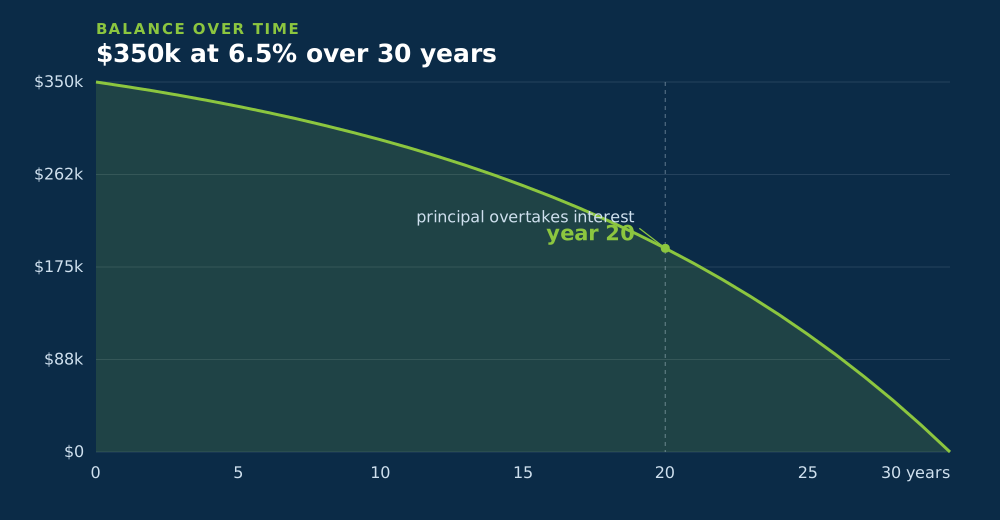
There are 52 weeks in a year, so a fortnightly plan means 26 payments. At half the monthly amount that adds up to thirteen monthly payments a year rather than twelve. The fortnightly timing itself contributes very little; the extra payment does the work.
The catch worth knowing
Because the benefit is the extra payment and not the schedule, you can produce the same outcome by dividing your monthly payment by twelve and adding that to each month - free, under your own control, with nobody in the middle. If a servicer wants a setup fee or a monthly charge to run a biweekly plan, you are paying for something your bank's standing order does for nothing.
Check how payments are applied
Some servicers hold both halves and post them together at month end. If they do, the timing benefit disappears and only the thirteenth payment remains. Ask before enrolling.
Guides that explain this
Written with the same engine, so every figure agrees with the calculator.
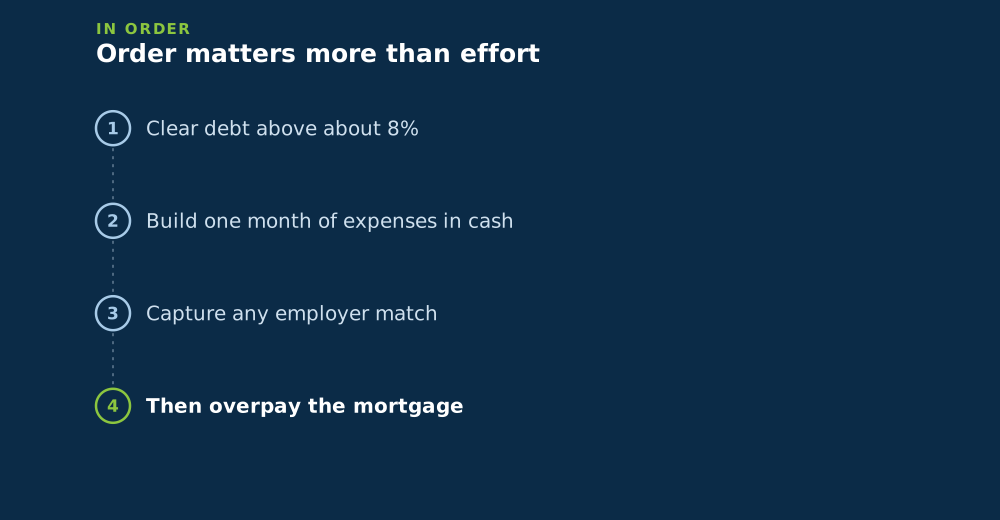 How to pay off your mortgage earlySix ways to clear a mortgage early, what each actually saves in dollars and years, and the cases where overpaying is the wrong move.11 min read
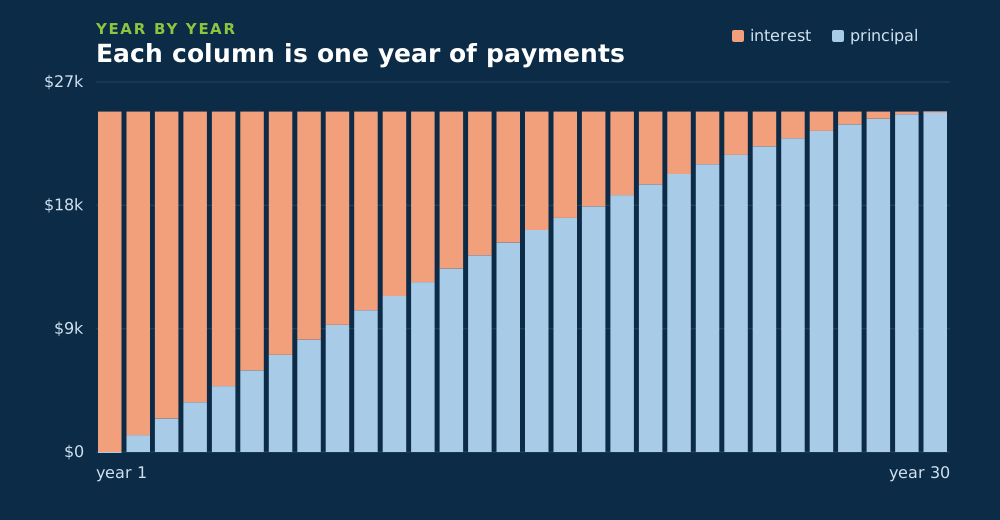 Amortization explained: where every payment actually goesA plain-English guide to amortization — why early payments are almost all interest, when the crossover happens, and how to read your own schedule with confidence.9 min read
Questions people actually ask
Does a biweekly mortgage really save money?
Yes, but not because of the fortnightly timing. Twenty-six half-payments equal thirteen monthly payments a year instead of twelve, and that extra payment is where almost all of the saving comes from.
Can I do this myself without signing up?
Yes. Divide your monthly payment by twelve and add that to every monthly payment, marked as principal. The result is very close to a biweekly plan and it costs nothing.
Is a biweekly setup fee ever worth paying?
Rarely. You are paying a third party to do what a standing order does. The one argument for it is discipline, if an automated plan is the only way you will keep it up.
Will my lender accept half payments?
Not all do, and some hold both halves and post them together at month end, which removes the timing benefit. Ask how payments are applied before enrolling.
Other calculators
- Amortization scheduleThe whole table, payment by payment, with extra payments and a CSV export.
- Extra payment calculatorWhat $200 a month is worth in interest saved and years removed.
- Refinance break-evenWhen the closing costs are recovered, and whether a new term quietly costs more.
- Compare three offersDifferent rates, terms and fees judged on total cost, not monthly payment.
- Mortgage calculatorPrincipal, interest, tax, insurance, PMI and HOA in one honest number.
- Auto loan calculatorTrade-in, negative equity, sales tax and dealer fees, all financed.