
Hard money loan calculator
A rate of 11% on a six-month loan is not 11%. Points are charged once regardless of how long you hold, which is what makes short-term money expensive in a way the headline rate hides.
Hard money loan calculator
Why the headline rate misleads
Hard money is quoted like a mortgage and behaves nothing like one. Two features do the damage.
Points are a fixed toll. Two points on a $212,500 loan is $4,250, charged at closing regardless of whether you repay in three months or twelve. On a three-month hold, that $4,250 is an 8% annualised cost on its own, before a cent of interest.
Interest is charged on the drawn balance, not the loan amount. Rehab money is released in stages against completed work, so you are rarely paying interest on the full facility. That is the one thing working in your favour, and most calculators ignore it, which overstates the cost by thousands.
What lenders actually quote
- Loan to cost — commonly 80–90% of purchase plus rehab. The gap is your cash.
- Loan to ARV — usually capped around 70%, and whichever constraint binds first is the one that matters.
- Points — 1.5 to 3, occasionally more for a first-time borrower.
- Rate — roughly 9.5–12% interest-only for residential bridge and rehab lending.
- Term — 6 to 18 months, with extension options that carry their own fee.
The extension trap
The single most expensive event in short-term lending is running past the term. Extensions typically cost another point or two plus a higher rate, and they arrive precisely when the project is already behind and the budget is already spent. Model the hold longer than you expect and check the deal still works; that is cheaper than discovering it later.
When hard money is the right tool
When speed or condition rules out conventional financing — a property that will not appraise, an auction with a fourteen-day close, a rehab too heavy for a 203(k). It is expensive money bought for a specific reason and repaid quickly. Used as long-term financing, the cost compounds against you in exactly the way this calculator shows.
Guides that explain this
Written with the same engine, so every figure agrees with the calculator.
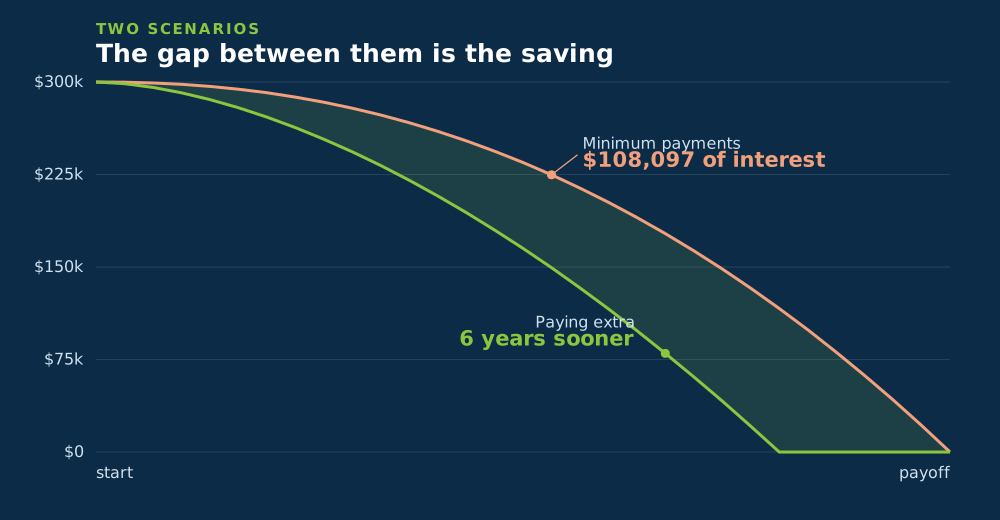 APR vs interest rate: what actually separates themWhat separates APR from the interest rate, which fees are included, and why APR quietly flatters a loan you will not keep for its full term.8 min read
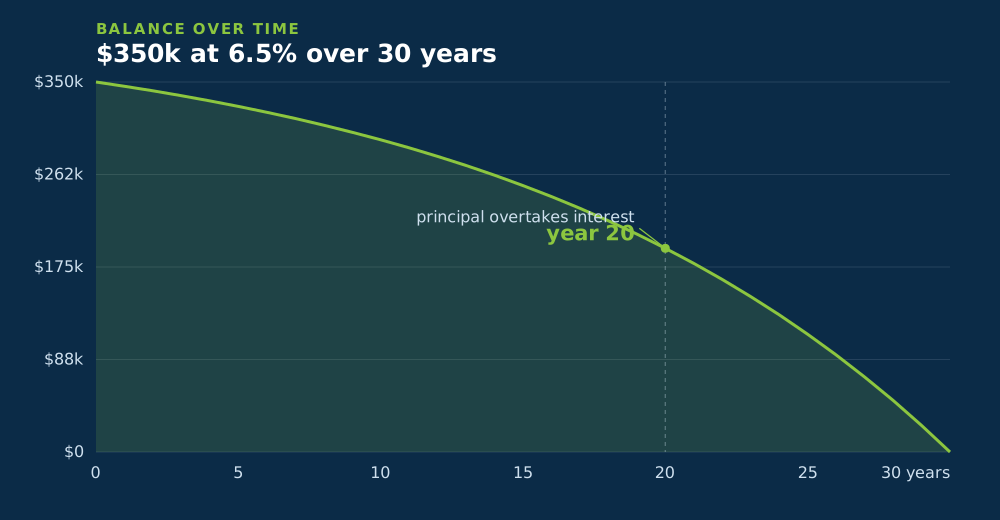 Student loan repayment without guessingRepayment plans compared on total cost, when refinancing federal loans is a mistake, and how capitalisation quietly inflates your balance.10 min read
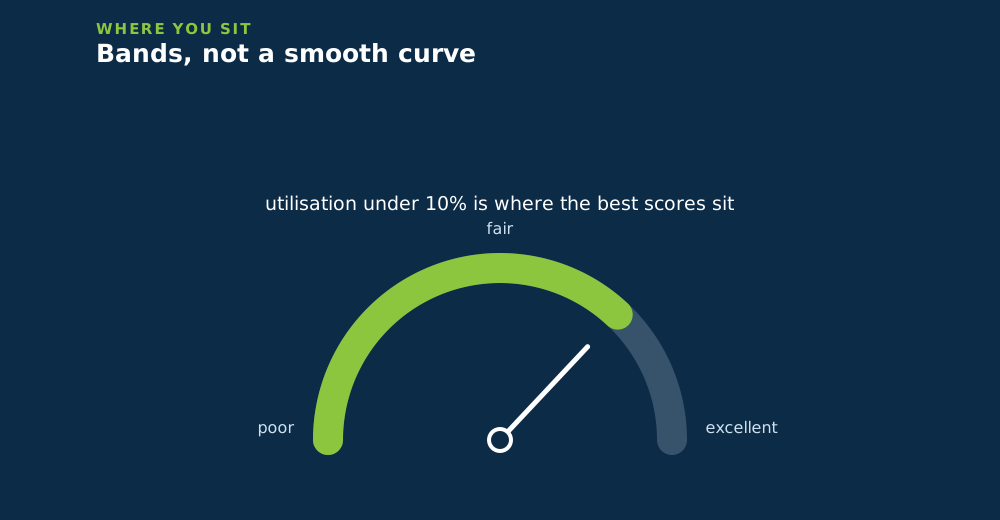 How your credit score sets your interest rateWhat a credit score is built from, how score bands translate into real rate differences and dollars, and which actions move a score quickly versus slowly.10 min read
Questions people actually ask
How much do hard money loans actually cost?
Typically 1.5–3 points at closing plus 9.5–12% interest-only. On a $212,500 loan held six months at 11% with 2 points, the total cost of the money is roughly $16,000 — an effective rate well above the headline.
Is interest charged on the whole rehab budget?
Usually not. Rehab funds are drawn in stages against completed work, so interest accrues only on the balance actually released. Over a term you often average around half the rehab line.
What is the difference between loan-to-cost and loan-to-ARV?
Loan-to-cost is a percentage of purchase plus rehab; loan-to-ARV is a percentage of the finished value. Lenders apply both and lend the lower of the two.
What happens if I cannot repay at the end of the term?
Most lenders offer an extension for another point or two plus a higher rate. It is the most expensive moment in the loan, and it arrives when the project is already over budget.